Fixed vs Floating Home Loan Interest Rate: Which One Should You Choose?
How fixed and floating home loan rates work in India, what the repo rate has to do with your EMI, and how to decide which suits you, with a rate-rise example.
When you sign for a home loan, one of the first choices is the type of interest rate: fixed or floating. Many borrowers pick whichever the bank offers first, then find out years later what that choice meant for their EMI.
The right answer depends on how long you plan to keep the loan, how much room your budget has and what you think interest rates will do, which nobody can predict reliably. This guide explains how each type works and how to pick one.
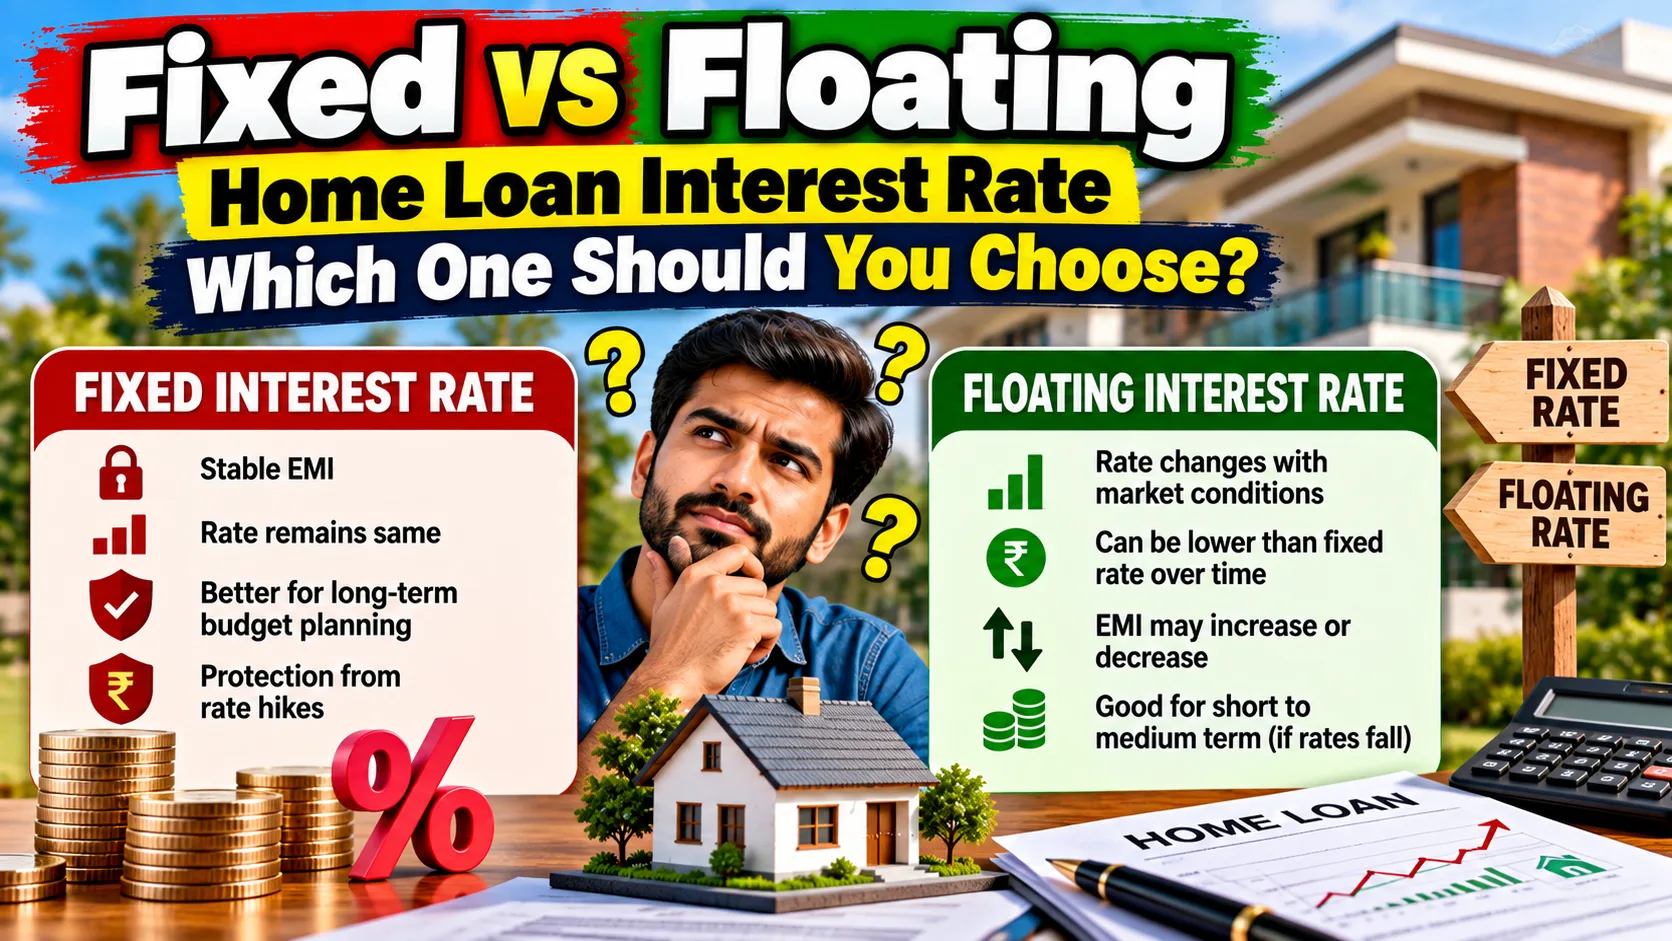
In short: A floating rate moves with a benchmark, so your cost can go up or down. A fixed rate stays the same for the agreed period, usually at a higher starting rate. Most home loans in India are floating, and the loan can often be switched later.
How a floating rate works
Since October 2019, the Reserve Bank of India has required banks to link new floating-rate home loans to an external benchmark, such as the RBI's repo rate. Most banks use the repo rate.
Your interest rate is made up of two parts:
Your rate = Benchmark (for example, the repo rate) + Spread
- The benchmark changes when the RBI changes its policy rate and the bank passes it on.
- The spread is the lender's margin, which is set when your loan is sanctioned. It covers the bank's costs and risk, and depends on your credit profile and the loan.
The rate is reset at fixed intervals, at least once every three months, and the new rate applies from the next reset date. When the benchmark falls, borrowers typically benefit within a few months. When it rises, the cost goes up too.
On 7 October 2026, the RBI's Monetary Policy Committee raised the repo rate by 25 basis points to 5.50%, according to published reports of the decision. Check the RBI's website for the current rate, because it can change at each policy meeting.
How a fixed rate works
With a fixed rate, the interest rate stays the same for a set period. Your EMI is predictable and you are protected from sudden increases.
There are some catches:
- Fixed rates usually start higher than floating rates.
- Some "fixed" home loans are fixed only for an initial period, such as the first few years, and then become floating. Ask exactly how long the fixed period lasts.
- If rates fall, you do not benefit unless you switch loans or the lender allows a conversion, which may involve a fee.
What a rate change does to your loan
Take a loan of ₹50 lakh at 8.5% for 20 years, with an EMI of ₹43,391.
If the rate rises to 8.75% and the bank keeps the EMI unchanged, your loan will take about 21 years to repay instead of 20. If the rate rises to 9%, it stretches to about 22 years and 3 months. If the bank instead keeps the tenure and raises the EMI, the new EMIs are as follows:
| Rate | EMI for 20 years |
|---|---|
| 8.50% | ₹43,391 |
| 8.75% | ₹44,186 |
| 9.00% | ₹44,986 |
Both routes cost you more. Extending the tenure feels painless because the EMI does not change, but it means more months of interest. The same applies in reverse when rates fall, so shortening the tenure is a good use of a rate cut.
Comparison at a glance
| Floating rate | Fixed rate | |
|---|---|---|
| Starting rate | Usually lower | Usually higher |
| EMI or tenure | Can change with rate resets | Stays the same during the fixed period |
| If rates rise | Your cost goes up | You are protected |
| If rates fall | You gain | You do not gain unless you switch |
| Best for | Longer loans, borrowers who can absorb changes | Borrowers who need certainty, short-term loans |
Rights you have as a borrower
The RBI has set out a framework for floating-rate loans to individuals. Its main points are:
- Lenders must tell you when the rate or EMI changes, and must explain how the change is handled.
- At the time of reset, you should be given the choice of increasing your EMI or lengthening the tenure, or a mix of both.
- You should be given the option to switch to a fixed rate, where the lender offers one, and the charges for doing so should be disclosed in advance.
- You can make part- or full prepayment. For loans to individuals for non-business purposes sanctioned or renewed on or after 1 January 2026, regulated lenders cannot levy pre-payment charges.
- Your lender must send you regular statements showing the principal repaid, interest charged, EMI, rate and remaining tenure. Ask for an updated schedule whenever your rate changes.
Read the sanction letter, because it sets out the benchmark, the spread, the reset period and any charges.
Older loans and switching to a lower rate
If your loan was sanctioned before October 2019, it may still be linked to the bank's older internal benchmark (MCLR or base rate), which tends to respond more slowly to rate cuts. You can ask your lender to move you to the external benchmark. Some lenders charge a small switching fee.
If your lender is charging a much higher spread than new customers are offered, you have three routes:
- Ask your bank to reduce the spread. Many agree to a small cut when you ask, especially if your credit score has improved.
- Transfer the loan to another lender (a balance transfer) at a lower rate. Compare the processing fee, legal charges and the time it will take before you decide.
- Prepay part of the loan to reduce the interest burden.
How to choose
Ask yourself:
- How long will I hold this loan? The longer the loan, the more a floating rate can swing in either direction. If you plan to repay in a few years, the starting rate matters more.
- Can my budget absorb a 1–2 percentage point rise? If not, choose a longer fixed period or keep a bigger buffer.
- Will I be able to prepay? If you will have spare money, a floating loan lets you cut costs without penalty.
- Is the gap between the rates large enough? A fixed rate that is only slightly higher can be a cheap form of insurance. A rate that is far higher is not.
For many borrowers, a floating-rate loan with a safety margin in the budget and a habit of prepaying works well. Choose fixed if predictability matters more than the lowest possible cost.
Frequently asked questions
Does the repo rate directly change my home loan rate?
If your loan is linked to the repo rate, yes. When the repo rate changes, your lender resets your rate at the next reset date, based on the terms in your sanction letter. Loans linked to older benchmarks may respond more slowly.
Can I switch from floating to fixed?
Many lenders allow this, usually for a fee and at the rate they are offering at the time. Ask what the new rate and the fee would be before you switch.
Is a fixed rate always safer?
It protects you from increases, but you pay for that with a higher starting rate, and you miss out if rates fall. It is safer for your budget, not necessarily cheaper.
Will my EMI change when the rate changes?
It depends on the lender's policy and the option you choose. Some keep the EMI the same and change the tenure, others change the EMI. See our EMI guide for how the numbers work.
Rates, rules and charges vary by lender and change over time. The figures here are illustrations. Confirm the current terms with your lender and read your sanction letter before you decide.