Joint Home Loan and Co-Ownership: Benefits, Risks and Tax Rules
Understand how a joint home loan works, who can be a co-applicant, how ownership share affects tax and stamp duty, and what risks to discuss before you buy a home together.
Buying a home with a spouse, parent, sibling or partner is common in India. Two incomes can mean a bigger loan, a lower EMI burden on each person and in some cases tax savings. But a joint loan also means shared responsibility, and a joint property means shared rights. Both need to be understood before you sign.
In short: In a joint home loan, every borrower is responsible for the whole loan, not just their share. For tax deductions, the person who is both an owner and a borrower can usually claim a share in line with the rules. Decide the ownership shares, the payment split and the exit plan in writing before you buy.
Co-borrower and co-owner are not the same
- Co-owner: a person whose name is on the property title (the sale deed).
- Co-borrower (co-applicant): a person who is a party to the loan and shares liability for repayment.
Banks usually want all co-owners to be co-borrowers, so that every owner is responsible for the loan. A person can be a co-borrower without being a co-owner in some cases, such as a parent who adds income to help the loan eligibility, but lenders have their own rules, and the tax benefits generally follow ownership. Ask your bank.
Who can be a co-applicant
Rules differ by lender. Commonly accepted co-applicants are:
- spouse,
- parents,
- siblings (sometimes), and
- adult children.
Friends or unrelated partners are accepted by some lenders only in limited cases, and lenders often prefer immediate family members. Check with your bank.
Benefits of a joint home loan
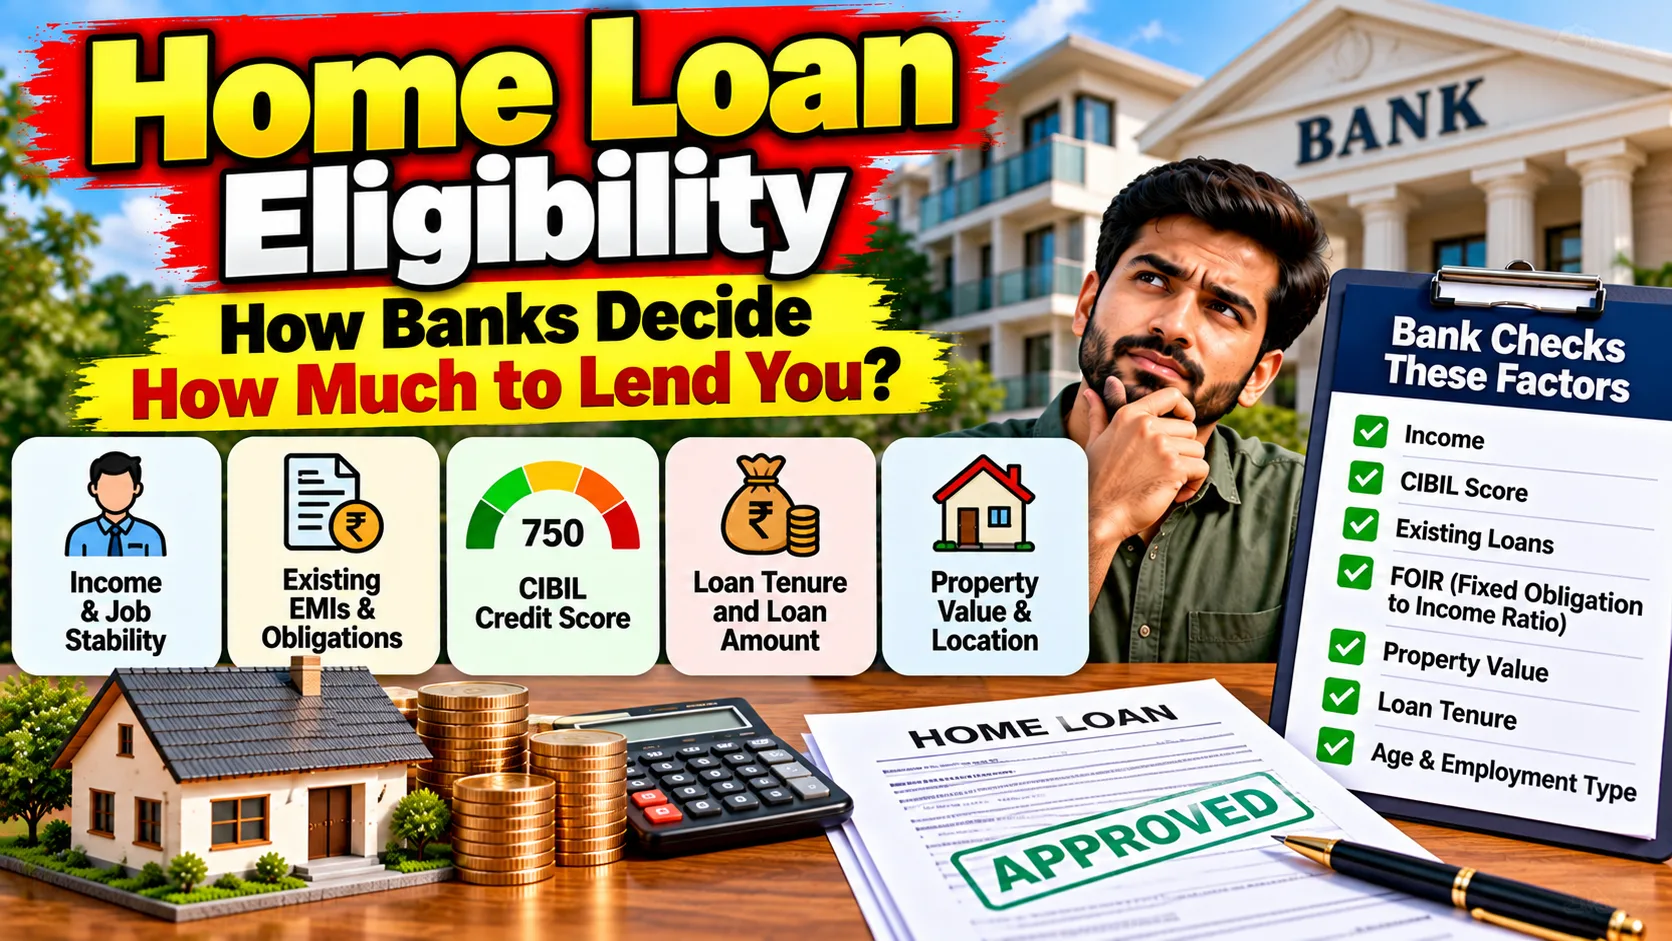
- Higher eligibility. The lender adds the incomes of both applicants, so you may qualify for a larger loan. See how banks decide your eligibility.
- Shared EMI. Both earning members can split the payment, easing the strain on one person.
- Tax benefits for each. If both are co-owners and co-borrowers, each can claim the deduction on interest and principal in line with the rules, in their own returns, up to the limits for each person. See home loan tax benefits.
- Possible concession on stamp duty and rate. Some states give a lower stamp duty when a woman is an owner, and some lenders give a slightly lower interest rate when a woman is a borrower. These concessions change, so check your state and your bank. See stamp duty explained.
- Joint credit history. Timely payments help both credit scores. See how to improve your CIBIL score.
- Easier inheritance planning when the title is clear and a co-owner is named.
Risks and downsides
- Joint and several liability. Each borrower is liable for the entire loan, not just half. If one person stops paying, the bank can ask the other for the full EMI.
- Credit score impact on both. A missed payment by one affects both borrowers' scores.
- Disputes in case of separation or conflict. If a marriage ends or a business partnership breaks, a jointly owned and jointly financed property can become a legal fight.
- Reduced borrowing room for each person. A joint loan counts against each borrower's other loan applications.
- Complicated sale. All co-owners must agree and sign to sell. One person cannot sell the whole property alone.
- Death or incapacity. The remaining borrower must continue to pay unless insurance clears the loan. See home loan insurance vs term insurance.
Ownership share, payment share and tax
Three things can be different, and mixing them up is a common mistake:
- Ownership share: the share each person holds in the property, as written in the deed. If the deed does not say, the law may treat owners as holding equal shares unless shown otherwise.
- Loan liability: each borrower is liable for the whole loan.
- Actual payment: who in fact pays the EMI.
For tax purposes, deductions are generally linked to the person who is the owner and the borrower and who actually pays. A person who pays nothing, or who is not an owner, cannot normally claim. If you want both of you to claim fairly, make sure that:
- both names are on the sale deed,
- both are co-borrowers,
- each pays from their own bank account, or the payments are clearly traceable, and
- the ownership shares are written in the deed.
The Income-tax Act has been renumbered, and limits apply. Confirm the current rules with a tax professional.
A simple example
A married couple buys a flat jointly, and the deed states 50:50 ownership. Both are co-borrowers, and both pay their share of the EMI from their own accounts. Each can claim a deduction on their share of the interest and principal, subject to each person's own limit under the law and the tax regime they have chosen. This can double the family's total deduction compared with one owner claiming alone, up to the limits. The actual figures depend on the current law.
Joint loan with a spouse who does not earn
If one spouse does not earn, the working spouse can take the loan alone and the non-earning spouse can be a co-owner without being a borrower, if the lender allows. But the non-earning co-owner cannot claim a deduction since they pay no interest. If the property is gifted or paid for by the other spouse, the tax rules on gifts and clubbing of income may apply. Ask a tax professional.
Joint loan with parents
Parents may join as co-borrowers to raise eligibility, especially for a young first-time buyer. If the parents are older, the lender may shorten the tenure. If the parent is only a co-borrower and not an owner, they typically cannot claim the deduction. If the parent is a co-owner, the property will become part of their estate, and the title and inheritance get more complex. Plan this in advance with a lawyer.
Joint loan with siblings or others
This can work, but write a co-ownership agreement that covers:
- ownership share of each person,
- who pays what and when,
- what happens if someone cannot pay,
- who lives in or rents out the property and how rent is shared,
- how and when the property can be sold, and
- what happens to a share when someone wants out or dies.
Before you sign: a checklist
- Decide the ownership shares and write them on the deed.
- Decide the payment split and how you will keep records.
- Check the bank's rules on co-applicants and its policies.
- Check stamp duty concessions for the owners in your state.
- Read home loan documents and the approval process for what each applicant must submit.
- Take insurance that covers both borrowers.
- Make wills so that shares pass according to your wishes. See sale deed vs agreement to sell vs GPA vs will.
- Discuss an exit plan: what if one wants to sell, move away or stop paying.
- Keep copies of all documents with both parties.
Frequently asked questions
Can I remove a co-borrower later?
Only with the lender's approval, and usually by refinancing the loan in one name or through a balance transfer. The person must also give up their share through a proper deed if they are a co-owner. See balance transfer guide.
Does a joint loan always reduce the interest?
No. A lower rate may be offered in some cases, such as with a woman borrower, but the main benefit is eligibility and shared burden.
If we are co-owners but only one of us pays the EMI, who gets the tax benefit?
Usually the person who actually pays and is both owner and borrower. Keep proof of who paid and ask a tax professional.
What happens if one borrower dies?
The loan remains and the surviving borrower and legal heirs are responsible. Insurance, if any, may clear it. Your lender and insurer can explain the process.
Lender rules, stamp duty concessions and tax laws differ and change. This guide is general information, not legal, tax or financial advice.