Home Loan Balance Transfer: When It Saves Money and When It Does Not
Should you move your home loan to another lender for a lower rate? See how a balance transfer works, the costs involved, worked savings examples and a simple break-even test.
If your home loan rate is higher than what new borrowers are getting, you may be overpaying every month. A balance transfer (also called a loan takeover or refinance) moves your outstanding loan to another lender at a lower rate. The new lender pays off the old one, and you start paying EMIs to the new lender.
It can save lakhs, but it also costs money and effort. This guide shows how to tell whether it is worth it for you.
In short: A balance transfer pays off when the rate gap is meaningful, a long part of the tenure is left and the one-time costs are small compared with the savings. Run the break-even test below before you apply. Also ask your current lender to cut your rate first.
How a balance transfer works
- You apply to the new lender for a takeover, with your documents and the old loan statement.
- The new lender checks your credit profile and the property, like a fresh loan. See home loan documents and the approval process.
- It issues a sanction letter and pays off the old lender.
- The old lender releases your original property documents to the new lender.
- You pay EMIs to the new lender at the new rate.
Many lenders also offer a top-up on the transferred loan if you need extra funds, usually at a rate that may differ from the base loan.
Costs to count
A balance transfer is not free. Add up all of these:
- Processing fee of the new lender, often a percentage of the loan amount plus taxes.
- Legal and valuation charges for the property check.
- Stamp duty and documentation charges for the fresh agreement and mortgage where applicable.
- Prepayment or foreclosure charges from the old lender. For floating-rate home loans to individual borrowers, RBI rules say lenders cannot charge prepayment penalties. Fixed-rate loans may carry charges, so check your agreement.
- Cost of insurance if the new lender bundles a policy.
In our examples below we assume a one-time cost of about ₹35,000 on a ₹40 lakh loan. Your real figure may be higher or lower, so get the numbers in writing from the new lender.
Worked examples
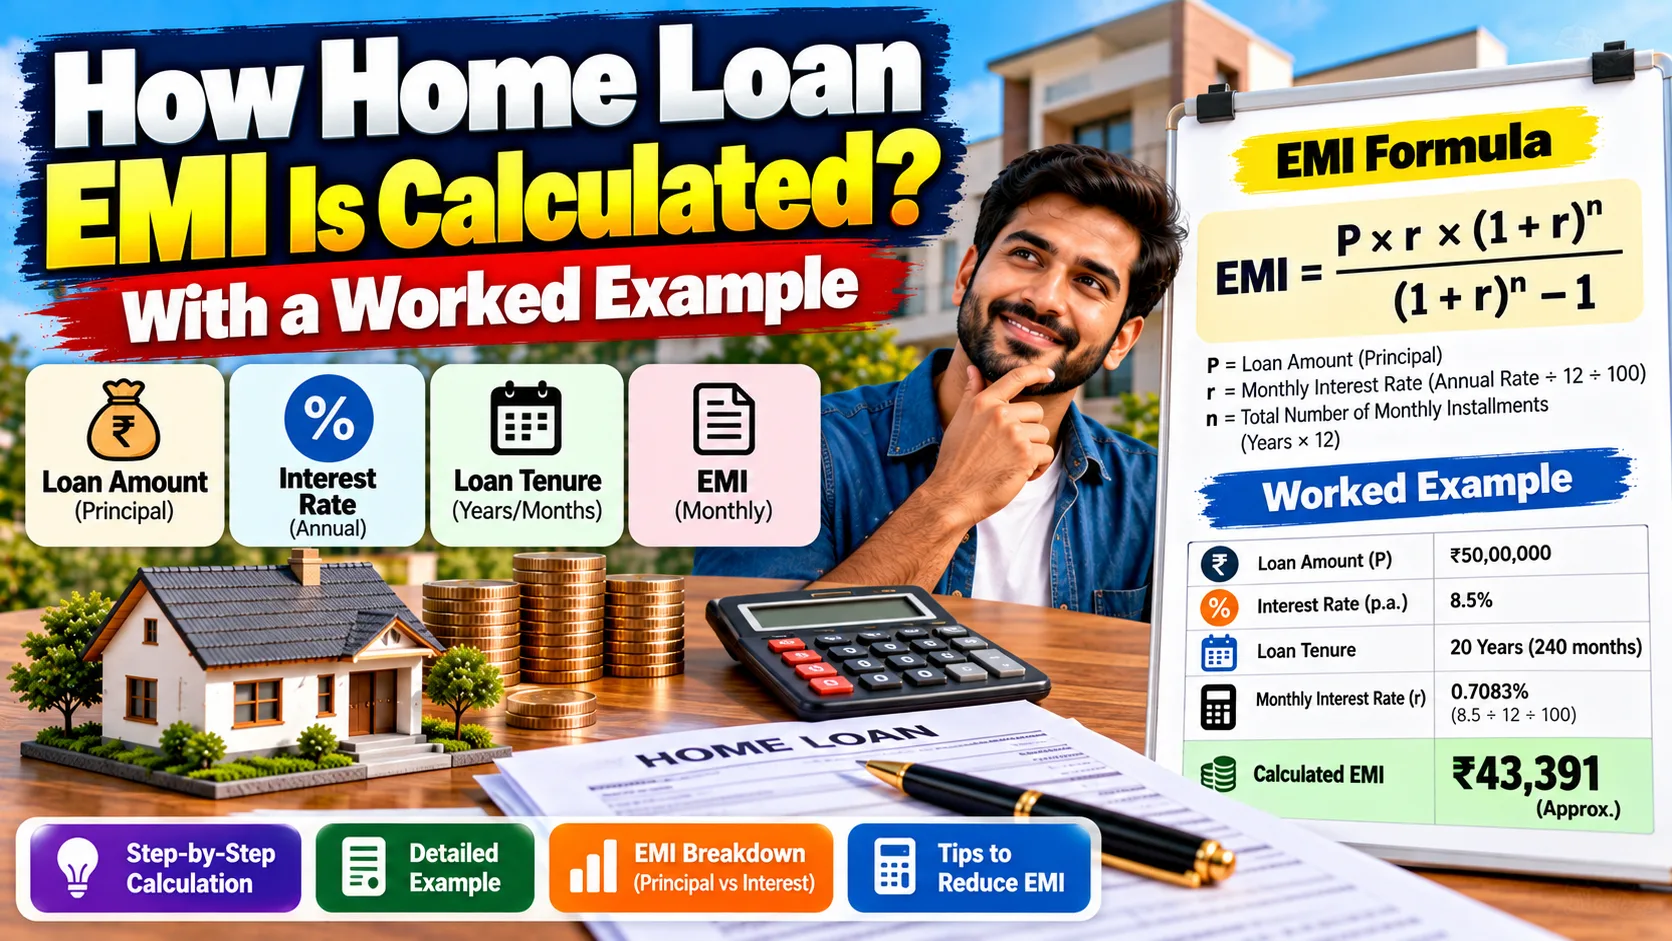
All three examples are for a ₹40 lakh outstanding loan. The EMI figures use the standard EMI formula. See home loan EMI explained.
| Situation | Old rate to new rate | Years left | EMI before | EMI after | Saving per month | Total saving over the remaining tenure | After ₹35,000 costs | Break-even |
|---|---|---|---|---|---|---|---|---|
| A. Big gap, long tenure | 9.25% to 8.50% | 18 | ₹38,085 | ₹36,218 | ₹1,866 | about ₹4.03 lakh | about ₹3.68 lakh | about 19 months |
| B. Small gap, short tenure | 9.00% to 8.50% | 5 | ₹83,033 | ₹82,066 | ₹967 | about ₹0.58 lakh | about ₹0.23 lakh | about 36 months |
| C. Tiny gap, long tenure | 9.00% to 8.75% | 18 | ₹37,458 | ₹36,836 | ₹622 | about ₹1.34 lakh | about ₹0.99 lakh | about 56 months |
What this tells you:
- Case A is a clear win. The gap is 0.75 percentage points, the tenure is long, and you recover the costs in about a year and a half.
- Case B is marginal. Even with a 0.5-point gap, there are only five years left, so the saving is small and the costs take three of the five years to recover.
- Case C shows that a small gap of 0.25 points can still add up over 18 years, but it takes almost five years to break even, and the saving disappears if you repay early or move to another loan again. These totals also assume you keep the loan to the end of the tenure. If you prepay it sooner, the saving is smaller.
The simple break-even test
- Find your new EMI at the new rate for the same remaining tenure.
- Subtract it from your current EMI to get the monthly saving.
- Divide the total one-time costs by the monthly saving to get the number of months needed to break even.
- If you expect to keep the loan well beyond that period, a transfer makes sense.
For example, ₹35,000 ÷ ₹1,866 is about 19 months.
When a balance transfer makes sense
- The rate gap is about 0.5 percentage points or more, and you have many years left.
- Your credit score has improved since you took the loan, so you now qualify for a better rate. See how to improve your CIBIL score.
- Your current lender refuses to reduce your rate.
- You want a better service, a transparent fee structure or a top-up on good terms.
When it does not make sense
- You are near the end of the loan, where most of each EMI is already principal and little interest is left to save.
- The rate gap is small compared with the fees.
- You plan to prepay a large part of the loan soon.
- The new lender's offer is a teaser rate that resets higher after a year or two. Read the terms.
- You have to restart a longer tenure that increases total interest, even though the EMI looks lower. Keep the tenure the same, or shorter, when you compare.
- You are claiming a government subsidy that will be lost on transfer. For example, the PMAY subsidy rules state that a borrower who transfers the loan to another lender cannot claim the subsidy again. See PMAY-Urban 2.0 guide.
Try this first: ask your current lender
Before you move, call your lender and ask for a lower rate. Many lenders let existing borrowers switch to a lower-rate scheme for a modest fee, and it avoids the legal charges and paperwork of a full transfer. Ask:
- What is the rate for new customers?
- What is the conversion or switch fee?
- Will the new rate apply from the next EMI?
- Is the fee payable in cash or added to the loan?
You may get most of the benefit without the hassle. Also check whether your loan is tied to the lender's external benchmark and how often it resets. See fixed vs floating rates.
Tax points
Interest on the new loan can be claimed as a deduction under the same conditions as the original loan, subject to the limits. If you take a top-up, the tax treatment depends on how you use the money. The Income-tax Act has been renumbered recently, so confirm the sections with a tax professional. See home loan tax benefits.
Checklist before you transfer
- Get the exact rate, fees and tenure in writing from the new lender.
- Calculate the break-even point.
- Ask the old lender for a rate cut or a switch option.
- Read the new lender's terms on rate resets and prepayment.
- Check for lost subsidies or benefits.
- Make sure the old lender returns the original documents after payoff.
- Keep the old loan closure certificate.
Frequently asked questions
Will a balance transfer hurt my credit score?
The new application causes a hard enquiry, which can lower the score slightly for a while. The old loan closing and the new one opening are normal events. Avoid applying to many lenders at once.
Can I transfer more than once?
Yes, if the numbers work each time. Costs add up, so repeated transfers for tiny gains rarely help.
Does the tenure restart?
It depends on the offer. You can usually choose the remaining tenure or a new one. Keeping the same tenure avoids paying more interest.
How long does it take?
It varies from a couple of weeks to over a month, depending on documents and how fast the old lender releases the papers.
All figures are illustrations based on the stated assumptions and ignore taxes, rate changes and charges that your lender may apply. This guide is general information, not financial advice.