Home Loan Documents Checklist and the Approval Process, Step by Step
A complete checklist of documents for a home loan in India and a clear walkthrough of the approval stages, from application to sanction, agreement and disbursement.
A home loan is not approved in a single step. The lender checks you, checks the property, issues a sanction, takes legal documents and then releases money in stages. Knowing the stages and keeping the papers ready can cut weeks from the process and prevent last-minute surprises.
In short: Keep identity, address, income and property documents ready. The usual path is application, verification, valuation and legal check, sanction letter, loan agreement and then disbursement. Read the sanction letter and the key facts statement before you sign anything.
Documents for the borrower
Requirements differ by lender and by profile, so use this as a base list and ask your bank for its exact list.
Identity and address (all applicants)
- PAN card.
- Aadhaar or another officially valid ID.
- Passport-size photographs.
- Proof of current address, such as a utility bill or rental agreement, where needed.
Income documents: salaried
- Recent salary slips, usually the last three to six months.
- Bank statements for the last six months, showing salary credits.
- Form 16 or income tax returns for the last two to three years.
- Employment details, and sometimes an offer or appointment letter.
Income documents: self-employed and business owners
- Income tax returns with computation of income for the last two to three years.
- Profit and loss statement and balance sheet, often certified by a chartered accountant.
- Bank statements for personal and business accounts, usually for 6 to 12 months.
- Proof of business existence, such as registration, GST returns or licence.
Other
- Details of existing loans and EMIs.
- Proof of down payment source, such as savings statements.
- For co-applicants: the same documents as above.
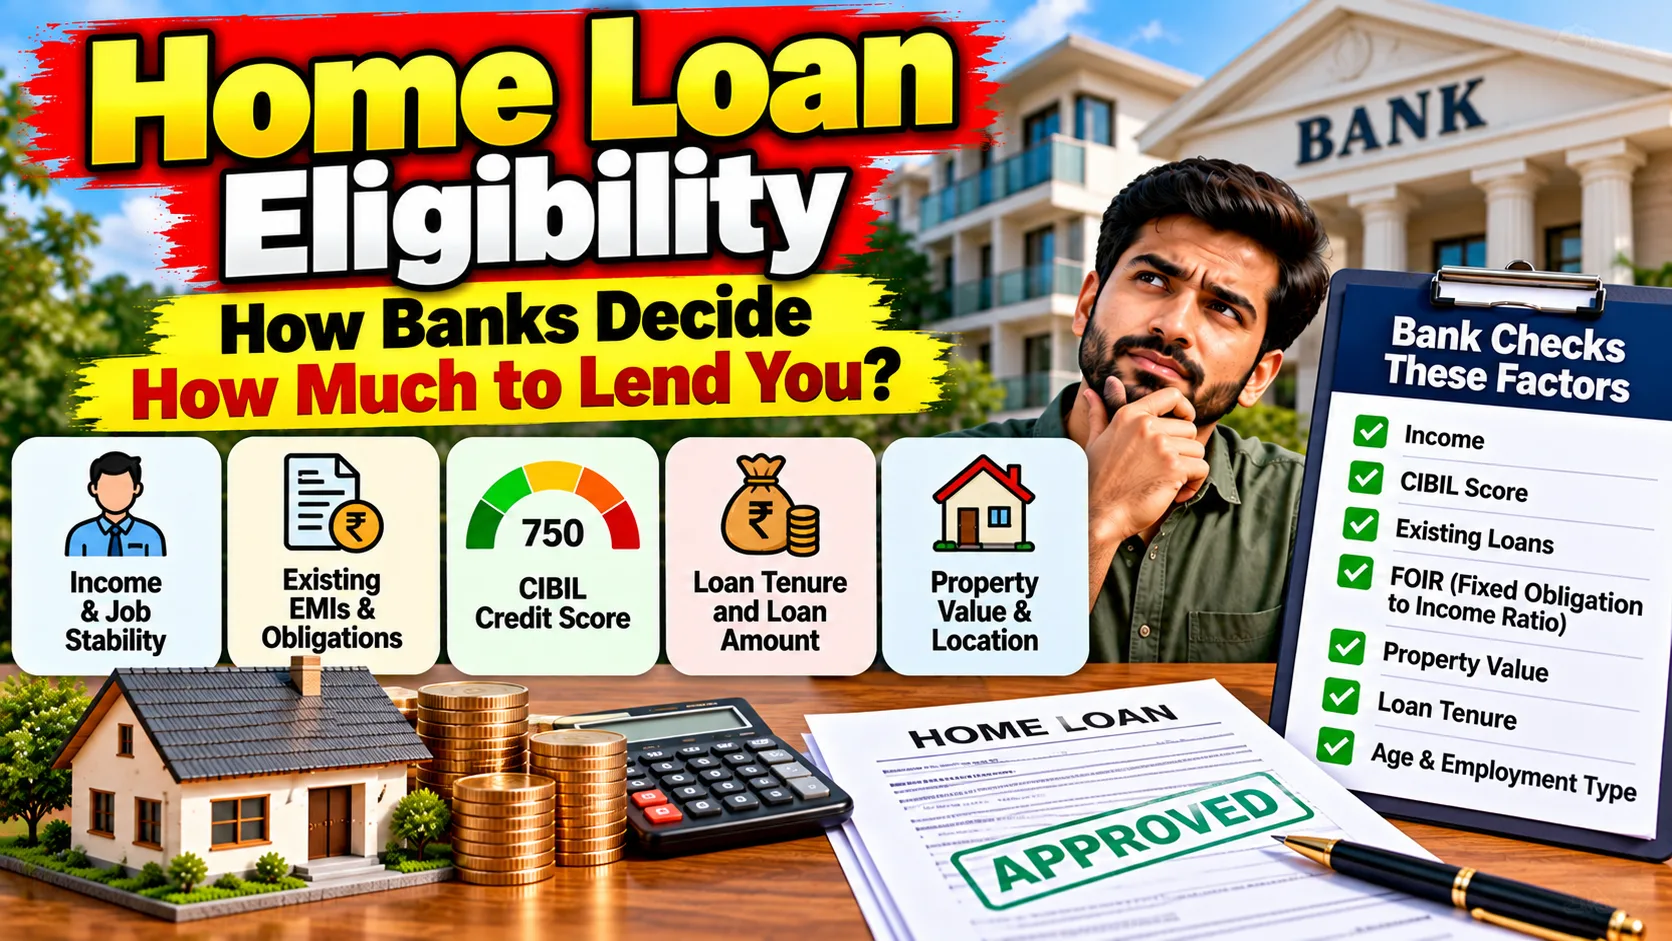
Your income and credit profile decide how much you can borrow. See how banks decide your eligibility.
Documents for the property
The lender will check that the property has a clear title and approvals. Typical papers are:
- Agreement for sale or sale deed (or the draft).
- Title documents: the chain of previous sale deeds for a resale property.
- Approved building plan and commencement or completion certificate.
- Allotment letter for a new flat, with the builder's payment schedule.
- Encumbrance certificate where applicable.
- No-objection certificate from the society, builder or existing lender.
- Property tax receipts and utility bills for a resale property.
- RERA registration details for an under-construction project.
If your lawyer has not yet checked these, do so before you pay a large token. See documents to check before buying property.
The approval process, stage by stage
1. Eligibility check and in-principle approval
You share basic details and the lender gives an estimate of the loan amount. Some banks call this an in-principle or provisional sanction. It is not a final approval, and it can change after verification.
2. Application and processing fee
You fill in the application and submit documents. Lenders usually charge a processing fee, often a percentage of the loan amount plus taxes, though many offer waivers or reduced fees at times. Ask what is refundable if the loan is rejected.
3. Verification of your profile
The lender verifies your identity, income, employment and credit history. It pulls your credit report, and may contact your employer or visit your home or office. Keep your phone reachable and your documents consistent. Mismatched names or addresses slow things down. Your credit score matters a lot here. See how to improve your CIBIL score.
4. Property valuation and legal check
The lender sends a valuer to assess the property's market value and a panel lawyer to check the title documents. The loan amount is based on the lower of the agreement value and the valuation, not on the price you agreed. If the valuation is lower than the price, you pay the gap from your own pocket.
5. Sanction letter
If everything is fine, the lender issues a sanction letter. It states:
- the sanctioned loan amount,
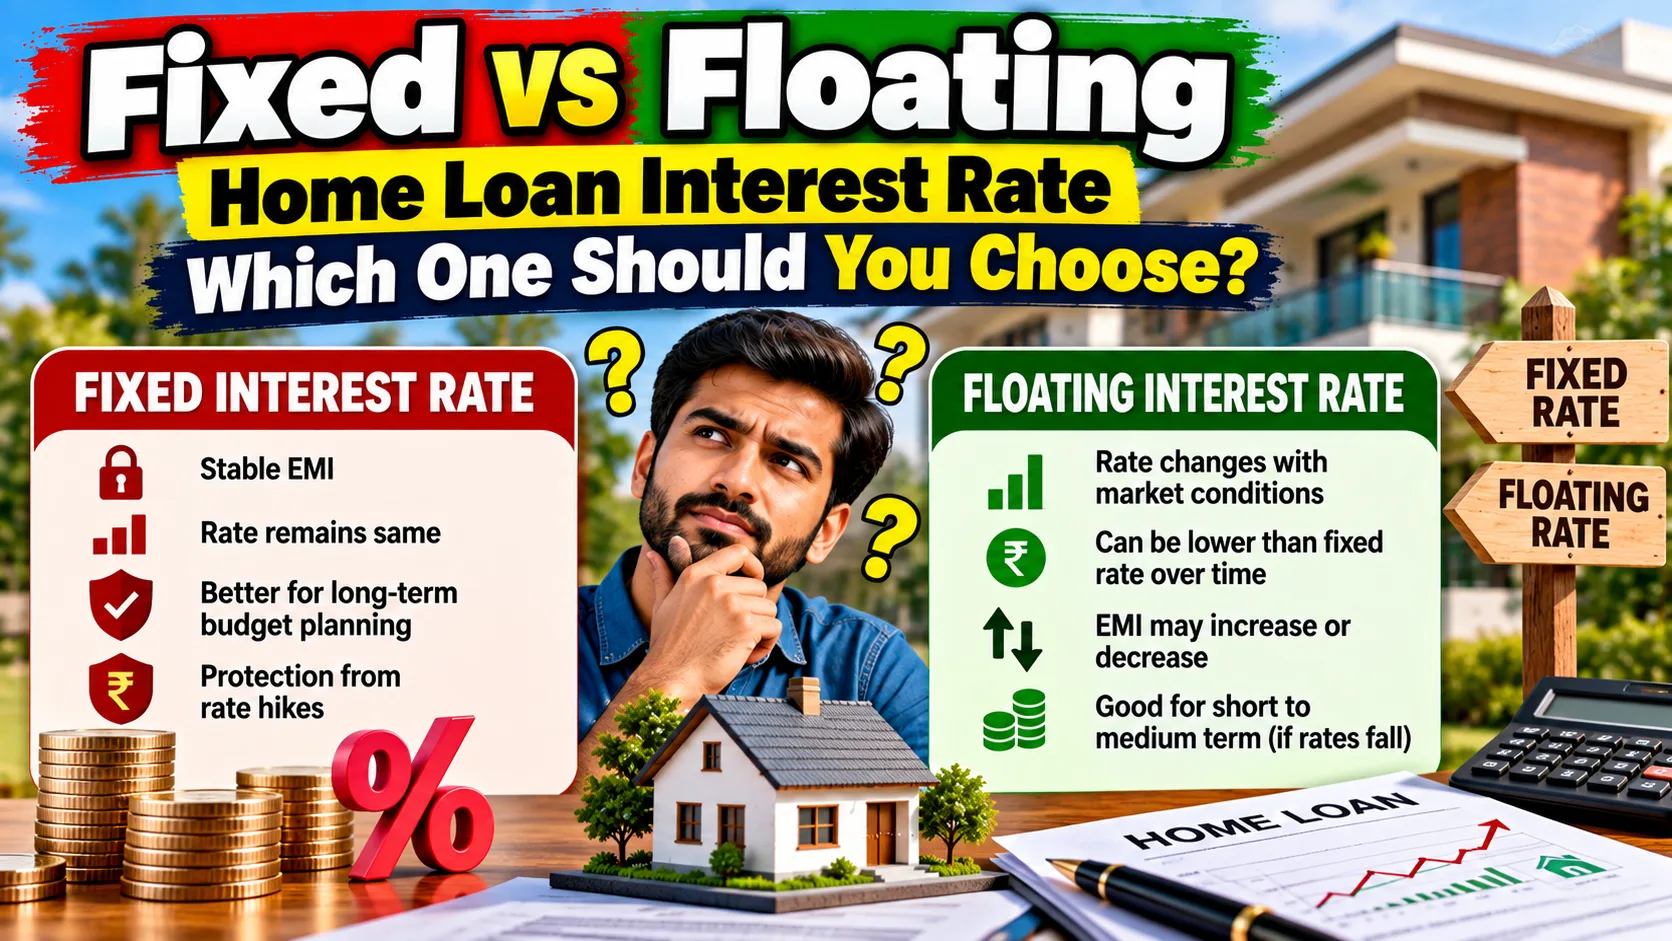
- the interest rate and whether it is floating or fixed,
- the tenure and EMI,
- the processing fee and other charges,
- conditions to be met before disbursement, and
- the validity of the sanction.
Read it fully and compare it with what you were told. Our guide on fixed vs floating rates helps you understand the rate terms.
6. Key facts statement and loan agreement
RBI rules require lenders to give borrowers a Key Fact Statement (KFS) in a standard format for retail and MSME loans, which includes the annual percentage rate (APR) covering interest and charges. The rule applies to new loans from 1 October 2024, so ask for it before you sign. Check the APR, the total cost, the prepayment terms and the details of any insurance bundled with the loan.
Housing finance companies also provide the most important terms and conditions. Take your time with the loan agreement. Do not sign blank forms.
7. Legal documentation and security
You sign the loan agreement and give the property papers as security. For a resale property, the lender usually keeps the original title documents until the loan is repaid. A mortgage may be created and registered where applicable. Charges can include stamp duty on the loan agreement and documentation fees.
8. Disbursement
- Ready property: the lender usually pays the seller directly, after the sale deed is registered, against the agreed documents.
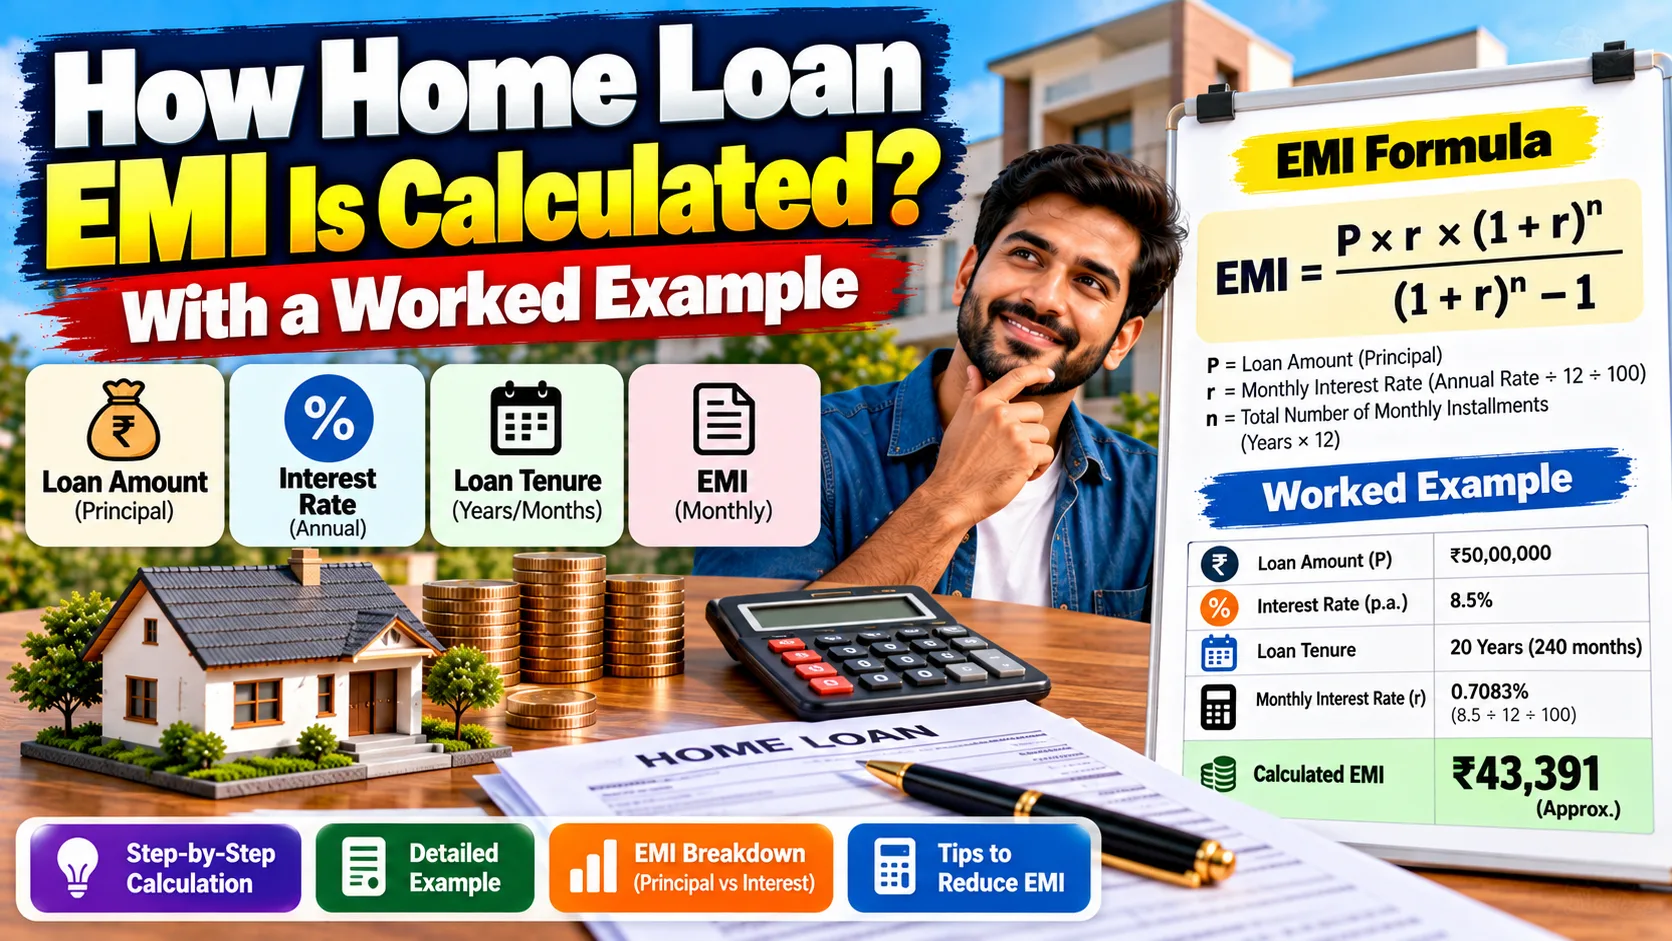
- Under-construction property: money is released in stages, linked to construction progress. You pay pre-EMI interest on the amount released until the last instalment. See home loan EMI explained and ready vs under-construction.
9. After disbursement
- Start paying EMIs on the agreed date and set up a standing instruction.
- Keep copies of the sanction letter, agreement and repayment schedule.
- When you finish repaying, collect the original documents and ask for a no-dues certificate.
How long does it take?
It can take from a few days to several weeks, depending on how complete your documents are, the property's legal status and the lender. Delays usually come from missing papers, a title problem or a mismatched valuation.
Tips to speed up approval
- Keep scanned copies of all documents in one folder.
- Make sure names and addresses are identical across PAN, Aadhaar and bank records.
- Clear small dues and check your credit report first.
- Choose a property that the lender already knows and approves.
- Avoid applying to many lenders at the same time, since each application can trigger a credit enquiry.
- Reply to queries within a day.
Red flags to watch for
- A lender asking for money to "guarantee" approval.
- Fees that were not mentioned earlier.
- Pressure to buy insurance or another product with the loan. Insurance is generally optional unless the law requires it. See loan insurance vs term insurance.
- Blank cheques or signed blank forms.
Frequently asked questions
What is the difference between in-principle approval and a sanction?
An in-principle approval is an early estimate. A sanction is the lender's formal offer after checking your documents, credit and property.
Can the lender change the rate after sanction?
For floating-rate loans, the rate follows the lender's benchmark. Read how and when the rate resets in the agreement.
Will the lender lend 100% of the property price?
Usually not. Lenders finance a part of the value and you pay the margin money from your own funds.
What if my loan is rejected?
Ask for the reason. Common causes are low credit score, high existing EMIs, insufficient income documents or a property with title issues. Fix the reason and apply again, or try a different property.
Document lists, fees and timelines differ by lender. This guide is general information, not financial advice.