How to Improve Your CIBIL Score Before Applying for a Home Loan
A practical guide to understanding and improving your CIBIL score before a home loan application, including how to read your report, fix errors and avoid common mistakes.
Your credit score is one of the first things a lender looks at. A good score can mean faster approval and a lower interest rate. A weak one can mean a rejection or a higher rate that costs lakhs over the life of the loan.
The good news is that a score is not fixed. With a few months of steady habits you can usually improve it. This guide explains how.
In short: Get your free credit report, check it for errors, pay all dues on time, keep credit card use low, avoid new loan applications and give your score a few months to recover before applying. A score of about 750 or above is generally seen as strong.
What the score is
A credit score is a three-digit number that summarises your credit behaviour. In India, the credit bureaus (TransUnion CIBIL, Experian, Equifax and CRIF High Mark) calculate it from information that banks and lenders report. The CIBIL score ranges from 300 to 900. Lenders set their own cut-offs, but a score of 750 or above is commonly seen as good for home loans.
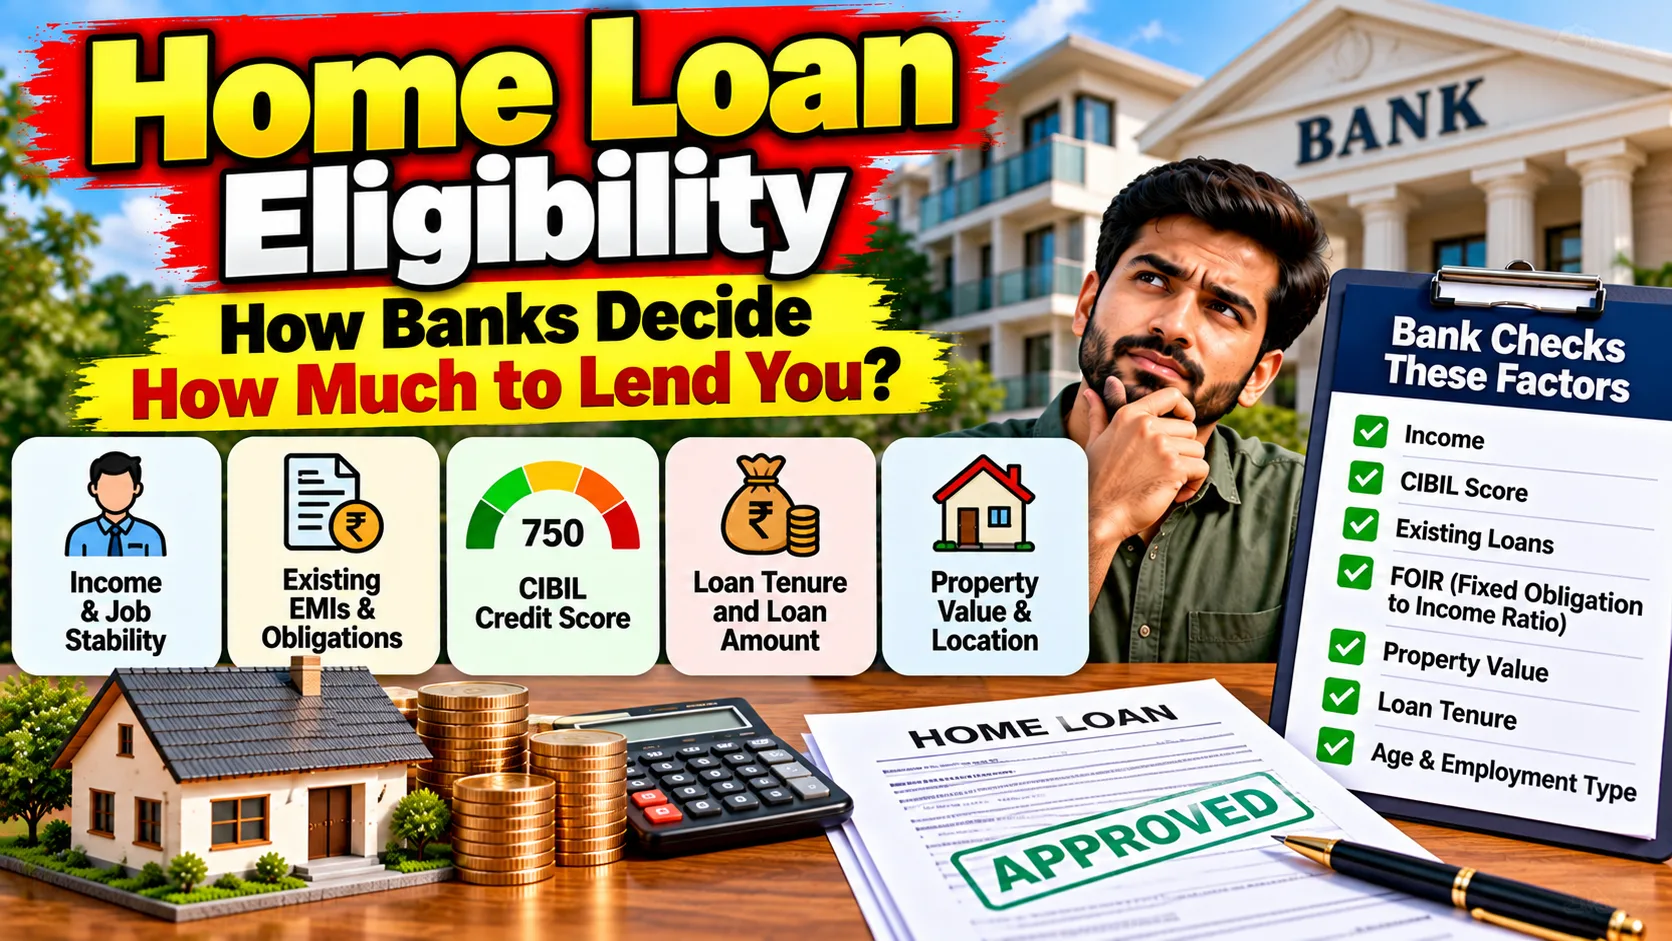
A score is only one factor. Lenders also look at income, existing EMIs and the property. See how banks decide your eligibility.
Step 1: Get your credit report
Every credit bureau is required to give you at least one free full credit report each year when you request it. Ask for the report from each bureau, because they can show different information. The report lists:
- your loans and credit cards, with limits and balances,
- your payment history, including late payments,
- any defaults, settlements or write-offs, and
- recent credit enquiries.
Read it carefully, line by line.
Step 2: Fix errors
Mistakes are common. Look for accounts that are not yours, loans that you closed but that show as open, wrong payment status and wrong personal details.
To dispute an error:
- Raise a dispute on the bureau's website or with the lender.
- Give supporting documents, such as a closure letter or a statement.
- Follow up. Under RBI rules the bureau and the lender must resolve the dispute within a set time, and delays can lead to compensation to you. Check the current rule on the RBI website.
- Get a fresh report after the correction.
Fixing a wrong entry can raise your score faster than anything else.
Step 3: Pay every due on time
Payment history has the largest effect on your score. Even one missed EMI or card payment can hurt.
- Set up auto-debit for EMIs and at least the minimum on cards.
- Pay credit card bills in full where you can.
- If you are late, pay as soon as possible, because the damage grows with the delay.
Step 4: Keep credit card use low
Credit utilisation is the share of your card limit that you use. Using a large part of your limit looks like financial stress.
- Many advisers suggest keeping use below about 30% of the limit, though this is a rule of thumb, not a rule of the bureaus.
- Pay before the statement date so a lower balance is reported.
- Ask for a higher limit if your income has grown, so that your utilisation falls.
Step 5: Clear or settle old dues properly
- Pay off overdue accounts. A defaulted account stays on your report and hurts approval.
- Avoid "settled" status where you can. A settlement means you paid less than owed, and lenders see it as a negative. If you must settle, get a no-dues letter and ensure the account is shown as closed.
- Do not close your oldest credit card without thinking, because the length of your credit history helps.
Step 6: Avoid new credit before you apply
Every time you apply for a loan or card, the lender makes a hard enquiry, which can lower your score a little for a while. A string of applications looks risky.
- Do not apply for new loans or cards in the three to six months before your home loan.
- Rate shop by asking lenders for an eligibility estimate, not a full application, until you are ready.
- Do not guarantee another person's loan lightly. If they default, it affects you.
Step 7: Keep a healthy mix and long history
A mix of secured loans (home, car) and unsecured credit (cards, personal loans), repaid regularly, shows you can handle credit. If you have no credit history at all, start small, with a card or a small loan, and use it responsibly for several months.
How long does it take?
Updates depend on when lenders report to the bureaus. Reporting has become more frequent, and RBI has asked lenders to report to the bureaus more often than before, so changes can appear within a few weeks. Real improvement, though, comes from months of steady behaviour. Plan three to six months, or longer if you have serious defaults. Check the current reporting frequency with the bureaus.
A simple plan
| Timeframe | Action |
|---|---|
| Today | Get reports from all bureaus, list errors and overdue accounts |
| Week 1 to 2 | Raise disputes, clear overdue amounts, set up auto-pay |
| Month 1 to 3 | Reduce card balances, avoid new credit, keep paying on time |
| Month 3 to 6 | Recheck the score, then apply to your lender with documents ready |
What if your score is low?
- Apply with a co-applicant who has a good score and income, such as a spouse. Their profile is considered along with yours.
- Reduce the loan amount or increase the down payment.
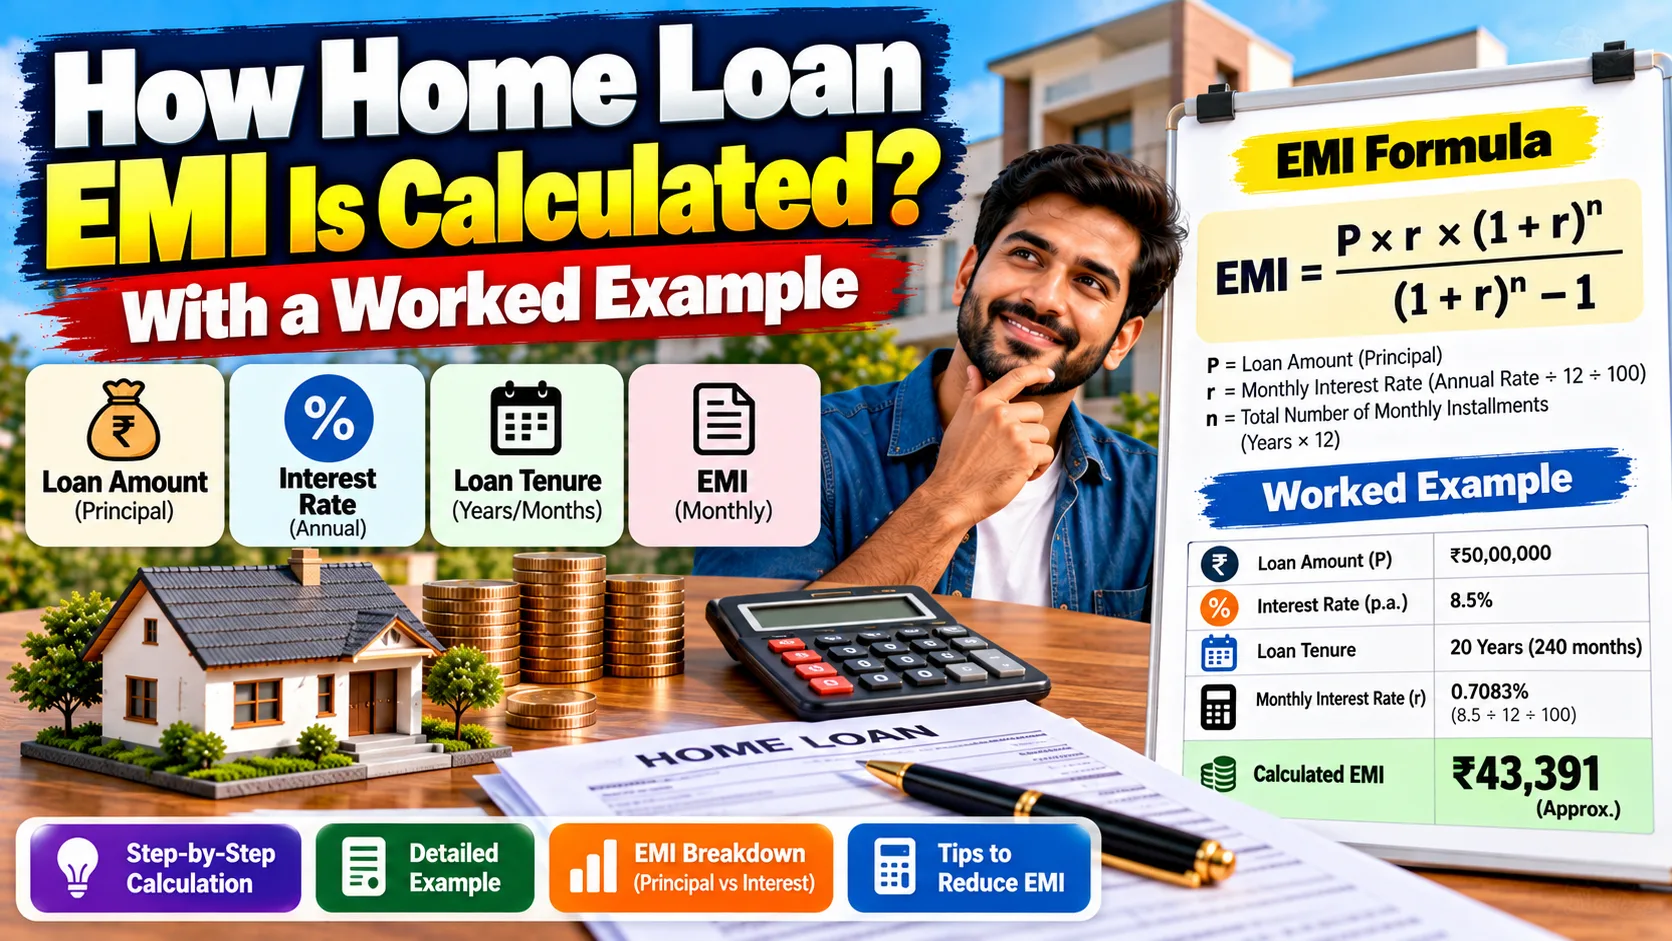
- Consider a smaller EMI by a longer tenure, but check the total interest. See home loan EMI explained.
- Talk to the lender. A lower score may mean a higher rate, not a rejection.
- Avoid agents who promise to "repair" your score for a fee. Only correcting wrong entries and building a good record works.
Mistakes to avoid
- Ignoring small bill dues.
- Using the card limit to the full every month.
- Closing old accounts without reason.
- Taking many loans in a short time.
- Never checking the report.
Frequently asked questions
Does checking my own score reduce it?
No. Checking your own report is a soft enquiry and does not lower your score. A lender's check when you apply is a hard enquiry.
What score is needed for a home loan?
There is no single cut-off. Many lenders prefer 750 or above and may offer better rates to higher scores, but they also weigh income, existing debts and the property.
Can I get a loan with no credit history?
Possibly, on the strength of income and a larger down payment, but it is harder. It is better to build a small, clean credit record first.
Will paying off a loan early improve my score?
Closing a loan in good standing is positive for your record, but the score effect varies. The main benefit is lower debt.
Scoring methods, free-report rules and dispute timelines are set by the bureaus and RBI and can change. This guide is general information, not financial advice.