Prepay Your Home Loan or Invest the Money? How to Decide
Should you use spare money to prepay your home loan or invest it? Compare the guaranteed saving with uncertain returns using a worked example, and use a simple decision checklist.
You get a bonus, a maturity payout or just have surplus savings. Do you throw it at your home loan to cut interest, or invest it and let it grow? People argue both ways, and the honest answer is that it depends on your loan rate, your risk comfort and your other financial gaps.
This guide shows how to think about it with numbers instead of opinions.
In short: Prepaying earns a certain, risk-free return equal to your loan rate. Investing can earn more but is not guaranteed. If your loan rate is high and your emergency fund, insurance and other goals are in place, prepaying is a solid choice. If you can take risk and your loan rate is low, investing may win. Never prepay by draining your emergency fund.
The basic idea
Every rupee you prepay stops charging interest at your loan rate. If your loan costs 8.75%, prepaying earns you a guaranteed 8.75% (before considering tax effects). Investing the same rupee has to beat 8.75% after tax and after allowing for risk, to come out ahead.
For floating-rate home loans to individuals, RBI rules say lenders cannot charge a prepayment penalty. Fixed-rate loans may have charges, so check your agreement before you decide.
Worked example
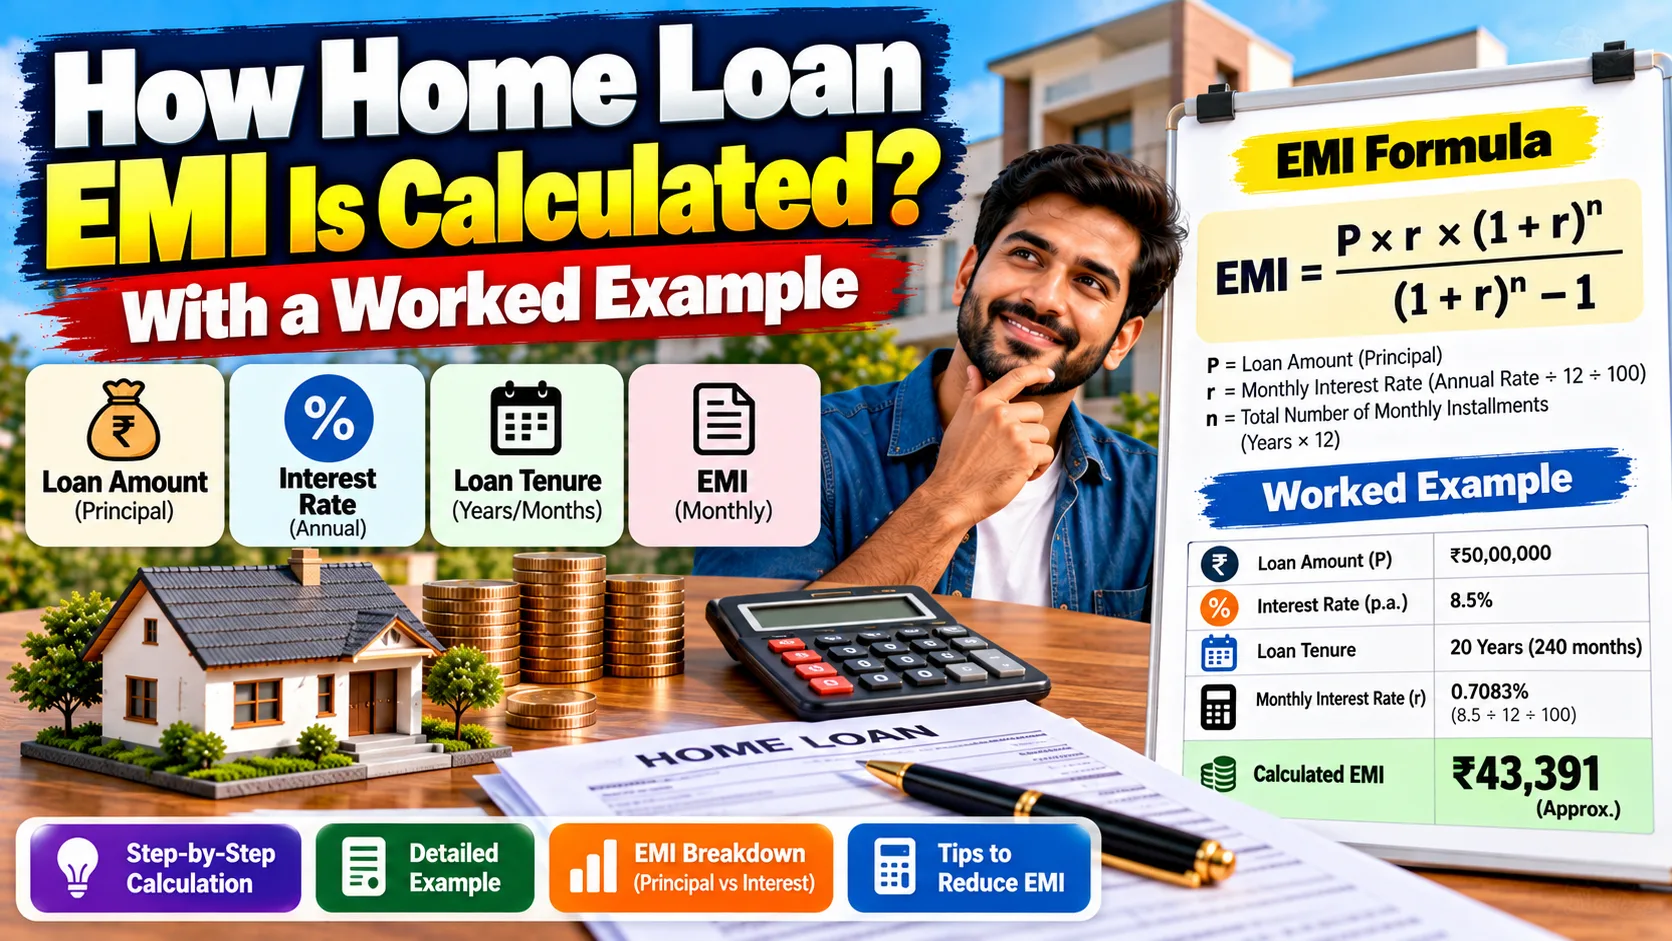
Take a ₹50 lakh loan at 8.75% for 20 years. The EMI is about ₹44,186. After 5 years, you have ₹10 lakh spare. The outstanding balance at that time is about ₹44.21 lakh.
Option A: Prepay ₹10 lakh and keep the same EMI. The balance falls to about ₹34.21 lakh, and the loan ends about 66 months early (in roughly 114 months instead of 180). After the loan ends, you invest the freed EMI of ₹44,186 each month until the original end date.
Option B: Invest ₹10 lakh for the remaining 15 years and keep paying the EMI as before.
Here is the money you have at the end of the original 20 years, ignoring tax and fees, for different investment returns:
| Assumed yearly return | Option A: prepay, then invest the freed EMI | Option B: invest the lump sum |
|---|---|---|
| 7% | about ₹35.4 lakh | about ₹28.5 lakh |
| 8% | about ₹36.5 lakh | about ₹33.1 lakh |
| 10% | about ₹38.7 lakh | about ₹44.5 lakh |
| 12% | about ₹41.0 lakh | about ₹60.0 lakh |
What the table shows:
- Option A does not depend on the market. Its result moves only slightly, as the freed EMI is invested at the assumed rate for a shorter time.
- Option B wins only when your investment earns clearly more than the loan rate, and the gap grows with time and return.
- The break-even sits at a yearly return a little under 9%, close to the loan rate. That is the key point: prepaying is roughly like investing at your loan rate with no risk.
These are simplified figures. Real investment returns vary year to year and can be negative, interest paid on your loan may give you tax benefits, and gains on investments can be taxed. A 12% return is not guaranteed. A bad stretch in the first few years can hurt a lump-sum investment badly.
Tax effects
- You may be able to claim a deduction for home loan interest and principal repaid under the tax law, subject to limits and the tax regime you choose. Prepaying reduces the interest you pay, and so, over time, the deduction you can claim. If you already hit the interest cap, extra interest above it gives no tax benefit, which makes prepaying more attractive. See home loan tax benefits.
- Investment gains are taxed, and the rate depends on the type of investment and holding period. Compare returns after tax.
- The Income-tax Act has been renumbered, so confirm the rules with a tax professional.
What to do first, before either
- Emergency fund. Keep several months of expenses in an accessible account. Once you prepay, you cannot take the money back from the loan.
- Insurance. Make sure health cover and term cover are in place. See loan insurance vs term insurance.
- High-cost debt. Pay off credit card balances and personal loans first, since their rates are much higher than a home loan.
- Short-term goals. Money you need in the next few years should not be locked in risky investments.
When prepaying is the better choice
- Your loan rate is high compared with safe returns.
- You are risk-averse and value the peace of mind of being debt-free sooner.
- You are close to retirement and want fewer fixed obligations.
- You have already hit the tax cap on interest.
- You are early in the loan, where most of each EMI is interest, so prepaying saves the most. See home loan EMI explained.
When investing is the better choice
- Your loan rate is low and you can reasonably expect a higher return over a long time.
- You have a long horizon (10 years or more) and can handle ups and downs.
- You have other goals, such as retirement or education, that need funding.
- You might need flexibility. Invested money can be withdrawn, while prepaid money cannot.
A middle path
You do not have to choose one. Many people split the money: put some into a prepayment each year and invest the rest. Some other ideas:
- Increase your EMI by a small percentage each year, in step with your income. This shortens the loan without a large single payment.
- Prepay a fixed amount every year, for example from your bonus.
- Choose to reduce tenure, not EMI, when you prepay. Reducing the tenure saves more interest. Reducing the EMI gives monthly relief but saves less overall.
- If your rate is much higher than new borrowers get, look at a balance transfer instead.
How to prepay properly
- Ask the lender for the exact outstanding balance and any charges.
- Make a written part-prepayment request or use the online option.
- Specify whether you want to reduce tenure or EMI.
- Get a revised repayment schedule and keep it.
- Check the next statement to confirm the amount was applied to the principal.
Frequently asked questions
Is it always better to be debt-free early?
Not always. Being debt-free gives peace of mind, but it is not always the highest-return choice. Balance it with your risk comfort and goals.
Should I prepay even if I have a PMAY subsidy or a subsidised rate?
Check the scheme rules first. A prepayment could affect the subsidy conditions. Ask the lender before you prepay. See PMAY-Urban 2.0 guide.
Is there a minimum prepayment amount?
Many lenders set a minimum, such as one EMI. Ask yours.
Can I prepay on a fixed-rate loan?
Often yes, but charges may apply. Read the loan agreement.
All numbers are illustrations with simple assumptions, no tax and no fees. Investment returns are not guaranteed. This guide is general information, not financial or tax advice.